October 2026
October brings warmer weather, longer days, and new spring growth. It’s a fresh chance to check in, take stock and prepare for the final stretch of the year.
The continuing concerns over inflation prompted the Reserve Bank to lift the cash rate by 0.25% to 4.6%, the highest level in 15 years. The RBA says that rising energy costs and stronger than expected economic activity also contributed to the decision.
Inflation remained above the RBA’s target range, with CPI surging to 4.0%, while the trimmed mean remained steady at 3.6%.
Consumer confidence declined 5.2% to 84.4 in September, down from 88.9 in August. This reflects concerns about cost-of-living pressures, higher interest rates and continued global uncertainty.
Australian share markets were weaker during the month with the S&P/ASX 200 retreating from the 9,000-point level as rising bond yields and expectations of higher interest rates took a toll on investor sentiment.
Oil prices remained high and volatile climbing back over US$100 a barrel, while the Australian dollar eased back towards US70 cents by month’s end.
RBA Announcement – September 2026
At its meeting today, the Board decided to increase the cash rate target to 4.60 per cent.
Inflation remains elevated and some of the upside risks flagged in August are materialising.
The conflict in the Middle East has broadened and global energy prices are now much higher than had been assumed in the August forecasts.
Please click here to view the Statement by the Monetary Policy Board: Monetary Policy Decision.
Please get in touch if you would like to discuss recent rates and how they may affect you, or if you would like to review your finance options.
Signals from the bond markets
If the financial markets could talk, then bonds would probably be saying: “We’re not convinced the story is over yet”.
Bond yields have been rising around the world as investors reassess the outlook for inflation, economic growth and government borrowing. The moves have been significant enough to influence mortgage rates, government finances and investment portfolios.
Experienced bond investors will be well aware of what’s been happening. For everyone else, the developments offer the chance to understand why professional investors see the bond market as one of the economy’s most important barometers.
You might never have bought a bond, researched a bond ETF or checked the yield on a government bond. But there’s a good chance that bonds already play a role in your investment portfolio through your superannuation account.
That’s one reason the recent attention on bond markets matters.
Looking back
From the early 1980s to around 2020, developed economies experienced one of the longest declines in interest rates and bond yields in modern history. Falling inflation, globalisation, technological advances and relatively stable economic conditions helped drive yields steadily lower.
Following the Global Financial Crisis and then the COVID-19 pandemic, many government bond yields fell to historically low levels. In some countries, investors were even willing to accept negative yields.
That changed dramatically from 2022 onwards as inflation surged. Central banks, including the Reserve Bank of Australia, responded by rapidly increasing interest rates.
The rapid increase in yields created short-term pain for existing bond investors but ultimately restored something that had been largely missing from bond markets for years: meaningful income.
Today, many commentators believe the era of ultra-low bond yields may be over. While inflation has eased from its peak, investors are increasingly questioning whether interest rates will return to the unusually low levels that prevailed during the 2010s.i
What’s happening in Australia?
Australian bond yields have moved higher during 2026 as investors responded to stronger than expected inflation and economic activity, and commentators are not confident that inflation will return quickly to the Reserve Bank’s target range.
Three-year government bond yields moved above 5 per cent, while 10-year bond yields approached levels not seen for more than a decade.ii
Higher yields affect far more than investment portfolios. Governments face increased borrowing costs, businesses pay more to raise capital, and lending rates throughout the economy may come under upward pressure.
The global picture
But Australia is not alone. Across the world, governments are issuing large amounts of debt to fund spending commitments, infrastructure projects and budget deficits.
Earlier this year, the International Monetary Fund (IMF) warned about the risks of geopolitical tensions, inflation uncertainty and rising levels of government debt.
Meanwhile, BlackRock notes that government borrowing is increasingly competing with private-sector demand for capital, helping push long-term yields higher in many countries. Its investment team believes that higher yields have created attractive income opportunities, but investors need to be more selective than in the past.
Understanding duration
‘Duration’ is one of the most important concepts in bond investing.
It measures how sensitive a bond’s price is to changes in interest rates. Generally speaking, the longer a bond’s duration, the more its price will move when rates change.
For example, a 10-year bond will usually experience greater price movements than a two-year bond if market interest rates rise or fall.
That helps explain why some bonds can experience significant short-term losses even when the issuer is considered financially secure. Investors often focus on credit risk, but interest-rate risk can be just as important.
The sharp rise in global yields over recent years has highlighted the importance of duration. Longer-dated bonds, which benefited hugely when rates were falling, were among the hardest hit when yields moved higher.
The bottom line
After years of being overlooked, bonds are once again demanding investors’ attention with higher yields providing more income than for much of the last decade.
At the same time, the rising yields are a reminder that bonds are not risk-free and that issues such as duration, inflation and government borrowing matter.
Although forecasts differ on the precise direction of interest rates, there appears to be broad agreement that investors should prepare for a more complex bond market.
i Fixed Income & Bond Market Outlook | BlackRock
ii Rising bond yields are punching a $10 billion hole in Australian government budgets | AFR
Mastering AI: it’s all in the prompts
It’s impossible to miss the buzz around Artificial Intelligence (AI). It’s changing the way we work and live – but if you haven’t yet started dabbling in it, it might seem a little intimidating.
The language sounds technical, the tools look unfamiliar, and the speed at which everything is evolving can make it seem as though you are already behind. It is completely reasonable to feel hesitant or avoid the platforms that use AI altogether.
However, if you are not using AI, you might be in the minority. The statistics show that roughly 66 per cent of people globally use AI regularly and that figure is growing all the time, so it might be worth overcoming your reticence.i
The truth is you do not need to have an in depth understanding of how AI works in order to use it well. At its core, AI responds to conversation. If you can explain a situation, describe a goal, or ask questions, you already have the skill that matters most.
Turn overwhelm into order
One of the most immediate ways AI can improve your life is by helping you organise your thinking when everything feels scattered. When your to do list feels endless and your priorities become a blur, it becomes difficult to get started.
For example, you might write:
“Here is everything on my mind this week. Turn this into a prioritised action plan for the next three days, highlighting what is urgent and what can wait.”
Seeing your responsibilities organised clearly often creates immediate relief. What felt chaotic becomes sequenced. And when you know what to focus on first, it becomes easier to begin.
Accelerate the way you learn
Learning something new often feels slow, not because it is too difficult, but because it lacks structure. Without a clear starting point, it is easy to consume random information and still feel unsure about what truly matters.
AI can help you create that structure. You might prompt:
“Create a simple 30-day roadmap to help me become competent in [skill]. Focus on fundamentals first and tell me what I can ignore at the beginning.”
That final sentence is powerful. Knowing what not to focus on prevents distraction. Instead of wandering through endless content, you follow a deliberate path.
Make decisions with greater clarity
Decision making becomes stressful when emotion clouds judgment, especially when the outcome feels important. In those moments, laying out the situation clearly and asking for a structured breakdown of potential risks, trade-offs, and implications can create valuable distance.
You could say:
“I am deciding between Option A and Option B. Break down the pros, cons, risks, and likely long-term implications of each.”
The goal is not to hand over responsibility, but to organise your thinking. Once trade-offs are laid out clearly, the right direction often feels less overwhelming.
Strengthen your thinking before you act
Another powerful way to use AI is to invite it to challenge your plans before the real world does. By asking where your strategy might fail or what assumptions you could be overlooking, you move from hopeful thinking to resilient thinking.
Try a simple prompt such as:
“Critique this plan. Where could it fail? What assumptions am I making?”
This can reveal blind spots you may not have considered. Identifying weaknesses early allows you to refine your approach while the stakes are still manageable.
Build systems that reduce mental strain
Many people rely on motivation to carry them toward their goals, yet motivation is unpredictable. AI can help you design simple, repeatable systems that remove the need to constantly decide what to do next.
For example:
“Design a simple weekly system that ensures I consistently make progress toward [goal], with clear actions and checkpoints.”
Instead of relying on how you feel each day, you follow a rhythm. Over time, small consistent actions compound into meaningful results.
The real shift
New tools often appear complex until we realise how simply they can be used.
When approached as a thinking partner rather than a technical system, AI becomes less about innovation and more about clarity. You do not need to be highly technical. You just need curiosity and a willingness to ask thoughtful questions – and be open to where the answers take you.
i Trust, attitudes and use of artificial intelligence |KPMG
The three phases of retirement: Key decisions at every stage
Retirement starts long before your last day at work
There are certain moments in life that reshape not just your finances, but the way you live.
Starting a family, moving overseas for a job, changing careers – retirement belongs in that same category in terms of its significance.
Traditionally, retirement has been viewed as a single milestone celebrated on the day you stop working. But in reality, it’s one of the longest and most significant chapters of your life – one that’s being reshaped by longer life spans, evolving retirement rules and rising living costs.
With Australians now living longer than ever, retirement can span decades, bringing new priorities, changing spending habits and different financial decisions along the way.1
That means retirement isn’t simply something to prepare for. It’s something you’ll need to navigate through.
Know what you’re aiming for
Before thinking about how you’ll fund retirement, however, it’s worth asking a simpler question: What kind of retirement do you actually want?
The Association of Superannuation Funds of Australia (ASFA) Retirement Standard provides a useful benchmark by estimating the annual income needed to support different retirement lifestyles.
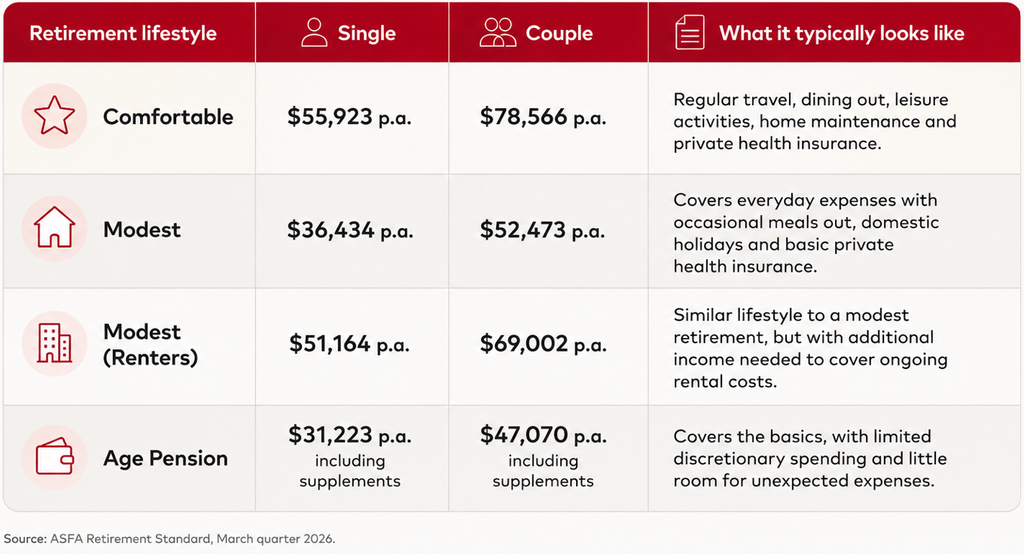
There’s no right or wrong answer. Some Australians dream of travelling the world, while others are happiest spending more time with family, pursuing hobbies or enjoying a slower pace of life closer to home.
The important thing is having a destination in mind. After all, it’s difficult to know whether you’re saving enough – or investing appropriately – if you don’t know what you’re trying to fund.
With that in mind, here are the three broad phases of retirement and the financial considerations that tend to become most important in each.
Phase 1: Building your retirement runway
The five to ten years before retirement are a critical time for financial planning.
This is when many of the biggest financial decisions get made – when to retire, what sort of lifestyle you want, whether you’re saving enough and how to make the most of your remaining working years.
Having a clear retirement plan can make a meaningful difference. A recent report has shown Australians who understand the steps they need to take for retirement are significantly more confident about funding their desired lifestyle and more optimistic about their future than those without a plan.
It’s also the time to take stock of your financial position.
While seven-figure super balances often grab headlines, they’re far from the norm. Australians aged 60 to 64 have a median super balance of around $236,126 for men and $174,655 for women.2
With many Australians approaching retirement with relatively modest super balances, making the most of available opportunities to contribute to super and strengthen retirement savings can be particularly valuable.
Here are several key questions to ask in the decade leading up to retirement:
- How much do I currently have in super and other investments, and will it support the lifestyle I want in retirement?
- Are there any big-ticket experiences I want to budget for, such as a luxury cruise, overseas travel or helping my children financially?
- Will I be in a position to pay off my mortgage before retirement?
- Do I want to stop working completely, or gradually transition through part-time or consulting work?
- Would downsizing or relocating improve my retirement lifestyle or financial position?
Phase 2: Putting your nest egg to work
Once retirement begins, your financial mindset will likely shift.
Instead of building wealth, the priority becomes generating an income that can support your lifestyle while ensuring your savings last for what could be another 20 or 30 years.
For many people, this can be an uncomfortable transition. After spending decades trying to grow your retirement savings, you’re now relying on them to fund your lifestyle
Retirees also need to consider sequencing risk – the impact a market downturn can have if it occurs early in retirement while you’re simultaneously drawing an income from your portfolio.
As a result, some retirees choose to maintain exposure to growth assets alongside defensive investments and cash, depending on their circumstances, objectives and tolerance for risk.
While liquidity can help fund day-to-day spending and reduce the need to sell investments during volatile markets, growth remains important because inflation continues long after your working life ends.
Your retirement income may also come from multiple sources including investments held outside super and, depending on your circumstances, the Age Pension.
Here are several key questions to consider as you approach and enter retirement:
- Where will my retirement income come from – super, investments, rental income, the Age Pension or a combination of these?
- Is my investment portfolio still appropriate now that my focus has shifted from building wealth to drawing an income?
- Can my income keep pace with inflation?
- Do I have enough cash or liquidity to cover unexpected expenses or periods of market volatility?
- Am I reviewing my spending regularly to ensure my savings remain sustainable over the long term?
Phase 3: Planning your legacy
As retirement progresses, financial planning often becomes about much more than investment returns.
Many retirees begin thinking more carefully about how they’ll be cared for if their health changes, whether their current home still suits their needs and how they want their assets distributed to loved ones.
While these conversations aren’t always easy, planning ahead can provide greater flexibility, reduce stress for your family and ensure your wishes are understood well before important decisions need to be made.
At some stage during retirement, these are some of the conversations worth having:
- Is my will up to date, and have I reviewed my beneficiary nominations?
- Have I considered how I would fund aged care or additional healthcare needs if they arise?
- Does my current home still suit my needs, or would another living arrangement be more appropriate?
- Have I appointed the right people to make financial or medical decisions if I’m unable to do so?
- Does my estate plan reflect the legacy I want to leave for my family and loved ones?
Strategies to consider
Your retirement plan doesn’t need to be perfect. The important thing is to start early, review it regularly and adapt it as your circumstances change.
Here are some practical strategies to consider. As always, it’s important to consider whether any strategy is appropriate for your personal circumstances and seek professional advice if needed.
- Start small. Retirement planning doesn’t have to happen all at once. Start by discussing a few key questions with your partner (or you can contact us) such as when you’d like to retire and how much super you may need.
- Review your super regularly. Make a habit of logging into your super account and checking your balance, investment options, fund performance and insurance cover.
- Make the most of super contributions. If you’re still working, additional concessional (before-tax) contributions could help grow your retirement savings.
- Understand carry-forward contribution caps. If your total super balance is below $500,000 and you meet the eligibility requirements, you may be able to use unused concessional contribution caps from the previous five financial years.
- Learn about downsizer contributions. If you’re 55 or over and meet the eligibility requirements, selling your home may allow you to contribute up to $300,000 each (or $600,000 per couple) into super.
Contact us if you have any questions.
1. ASFA Retirement Standard Budgets for various households and living standards for those aged 65-84 (March quarter 2026)
2. Median super balance, by age and sex, 2023–24 financial year – Australian Taxation Office
Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd
Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.
© 2026 Vanguard Investments Australia Ltd. All rights reserved.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
Why Transition to Retirement deserves a second look
For many people approaching retirement, the transition from full-time work to retirement is no longer a sudden stop. Instead, it’s often a gradual process that involves reducing work hours, maintaining cash flow and continuing to build retirement savings.
One strategy that can support this approach is a Transition to Retirement Income Stream (TRIS or TTR).i
While TTR strategies have been available for many years, they are often overlooked despite offering valuable flexibility for people in their 60s who are still working.ii
What is a TTR strategy?
A TTR strategy allows you to access some of your superannuation while continuing to work, provided you have reached your preservation age. For anyone born on or after 1 July 1964, preservation age is 60.iii
The arrangement works by transferring part of your super balance into a TTR pension account. You then receive regular pension payments while continuing to earn employment income. This can help replace lost income if you reduce your working hours or supplement your cash flow while making additional contributions to super.
Unlike a standard retirement-phase pension, a TTR pension has restrictions. Generally, you must draw a minimum pension each year and cannot withdraw more than 10 per cent of the account balance annually. Lump-sum withdrawals are generally not permitted while the TTR remains in the pre-retirement phase.iv
Who might benefit?
A TTR strategy may suit people who:
- want to reduce their working hours without a significant drop in income
- are approaching retirement but are not ready to stop work completely
- earn a moderate to high income and wish to boost superannuation through salary sacrifice
- want greater flexibility in planning their transition from work to retirement.
For example, someone aged 60 might decide to move from working five days a week to three days a week. By drawing a pension from their super, they can help replace part of their lost income and ease gradually into retirement.
Combining work income and pension payments
One of the key attractions of a TTR strategy is the ability to combine employment income with pension payments.
If you are aged 60 or over, pension payments received from a TTR income stream are generally tax-free in your hands. Instead of experiencing a substantial reduction in disposable income, a tax-free pension payment can help bridge the gap.
The tax-saving strategy
Another commonly used TTR strategy involves salary sacrifice.v
In this approach, an employee diverts part of their salary into superannuation through concessional contributions, which are generally taxed at 15 per cent within the super fund. The reduction in take-home pay is then partially replaced through tax-free TTR pension payments.
For people on higher marginal tax rates, this may improve tax efficiency because income that would otherwise be taxed at personal rates may instead be contributed to super and taxed at a lower rate. The TTR pension can then be used to maintain cash flow.
In some circumstances, this strategy may also help increase retirement savings while maintaining a similar standard of living before retirement.
Is a TTR strategy right for you?
A Transition to Retirement strategy can provide valuable flexibility for people who want to scale back work, supplement their income or potentially improve the tax efficiency of their retirement planning.
But the benefits depend heavily on individual circumstances, including age, income level, super balance, retirement objectives and tax position. What works well for one person may offer little benefit for another.
If you are approaching retirement and would like to explore whether a TTR strategy could help you achieve your goals, please contact our office. We can help assess whether the approach aligns with your broader retirement and financial planning objectives.
i Transition to retirement | ATO
ii iii Transition to retirement – Moneysmart.gov.au
iii Preservation age | ATO
iv TRIS requirements | ATO
v Using TTR to save on tax | Moneysmart
Ensure your estate planning reflects your wishes
Many people are surprised to learn that some of their largest assets may not be covered by their will. With recent changes affecting testamentary trusts and ongoing complexity around superannuation death benefits, now is a good time to review your arrangements.
New rules announced in the 2026-27 Federal Budget, combined with the growing complexity of superannuation death benefits, mean that it’s worth reviewing your arrangements to make sure your wishes can be carried out.
Testamentary trusts under the spotlight
Testamentary trusts have long been a popular estate planning tool because they can provide asset protection, flexibility and potential tax advantages for beneficiaries, particularly children.
The 2026-27 Federal Budget announced a new 30 per cent minimum tax on discretionary trusts, including testamentary trusts (those established by a will), from 1 July 2028.i
Following an outcry over what some called a “death tax”, the government announced exemptions for testamentary trusts, along with others including fixed trusts, special disability trusts and charitable trusts.ii
While the final shape of the rules remains uncertain, the Budget changes highlight the importance of ensuring estate planning arrangements are reviewed regularly.
The risks of an outdated will
Many people prepare a will and then leave it in a drawer for decades. But your personal and financial circumstances can significantly change over time.
Marriage, divorce, the birth of children or grandchildren, the death of beneficiaries, changes in asset ownership, or business succession arrangements can all affect whether an existing will still achieves the intended outcome.
Outdated wills can result in assets passing to unintended beneficiaries, family disputes and missed opportunities to achieve tax-effective outcomes.
So, review your will regularly and particularly after major life events occur.
Who gets your super?
One of the most common estate planning misunderstandings is assuming superannuation automatically forms part of an estate.
In most cases, superannuation benefits are not governed by your will. Instead, the trustee of the super fund determines who receives the death benefit unless a valid nominated beneficiary is in place.iii
A binding death benefit nomination allows you to direct the trustee of your super fund to pay your death benefit to specific beneficiaries.
Without a valid binding nomination, the trustee generally has discretion to decide who receives the benefit, subject to the fund’s governing rules and superannuation law.
Not all nominations remain effective indefinitely. Some funds require nominations to be renewed periodically, while others allow non-lapsing nominations.
Who qualifies as a dependant?
For superannuation purposes, the definition of a dependant is often different from what you might expect.
Generally, dependants may include:
- a spouse or de facto partner
- former spouses in some circumstances
- children of any age
- individuals who are financially dependent on the deceased
It may also include people in an “interdependency relationship” with the deceased. An interdependency relationship can exist where two people have a close personal relationship, live together and provide financial or domestic support to one another.iv
Importantly, being a beneficiary under a will does not automatically make someone a superannuation dependant.
The tax consequences can be significant
The tax treatment of superannuation death benefits depends heavily on who receives the money.v
If a death benefit is paid to a tax dependant, the benefit is generally received tax-free. Tax dependants include spouses, children under 18 years of age and people who were financially dependent on the deceased or in an interdependency relationship.
But adult children are often surprised to learn they may not qualify as tax dependants. If an adult child is financially independent, tax may apply to some components of a lump-sum superannuation death benefit.
As super balances continue to grow, the potential tax difference between payments to dependants and non-dependants can be substantial. This makes beneficiary nominations and estate planning decisions particularly important.
A coordinated approach is essential
Effective estate planning requires consideration of more than just a will. Superannuation nominations, testamentary trust structures, tax consequences and changing family circumstances should all form part of the conversation.
A regular review can help ensure your estate plan remains aligned with your objectives, takes account of current legislation and minimises the risk of unintended outcomes for your beneficiaries.
Please get in touch for information and advice about your estate planning and to confirm that it reflects your wishes.
i Introducing a minimum tax on discretionary trusts | ATO
ii Discretionary trusts reform implementation | Treasurer
iii Who gets your super if you die | Moneysmart
iv Superannuation interdependency relationships | AFCA
v Superannuation death benefits | ATO


 207 Bunda Street, Cairns QLD 4870

